Investment gets more selective
7th to 11th September

Leeds office redevelopment: Network Rail invests in upgrading existing workspace
Across this week's stories, investors, occupiers and public bodies are committing capital where there is a clear long-term case for doing so. Existing buildings are being upgraded, corporate estates consolidated, obsolete sites repurposed. Meanwhile, new developments are increasingly expected to demonstrate why location and specification make sense.
Network Rail is investing more than £40m in the redevelopment of Princes Exchange beside Leeds City Station. Willmott Dixon will replace the building's glazed façade and roof, overhaul its services and complete an internal fit-out, taking its EPC rating from D to A.
Rather than abandon an ageing building for new construction elsewhere, Network Rail is investing heavily in an existing asset in an exceptionally well-connected city-centre location.
Media conglomerate Sky, meanwhile, is taking the consolidation route. Its new 15-acre Livingston Campus will replace four buildings at Kirkton Campus and leased space at Alba Campus, bringing operations together within more than 21,000 sq m of new workplace.
These are different projects, but they point towards the same change in corporate property strategy. Major employers are becoming more deliberate about which offices they retain and where they invest. Fewer, better-performing workplaces with strong connectivity, modern facilities and a clear organisational purpose increasingly appear to be winning capital.
Plymouth Civic Centre takes the reuse argument further. The Grade II listed tower has stood empty since 2015, but Morgan Sindall has now been appointed to begin a £6.49m first phase of works that will ultimately support its conversion into 144 homes alongside a new City College Plymouth Blue Green Skills Hub.
It is a challenging building with all the complications that come with adapting a listed high-rise structure to modern safety and performance requirements. Demolition would undoubtedly offer a simpler answer in many circumstances. Instead, Plymouth is attempting to preserve a major piece of its post-war architecture while giving it completely different economic and social functions.
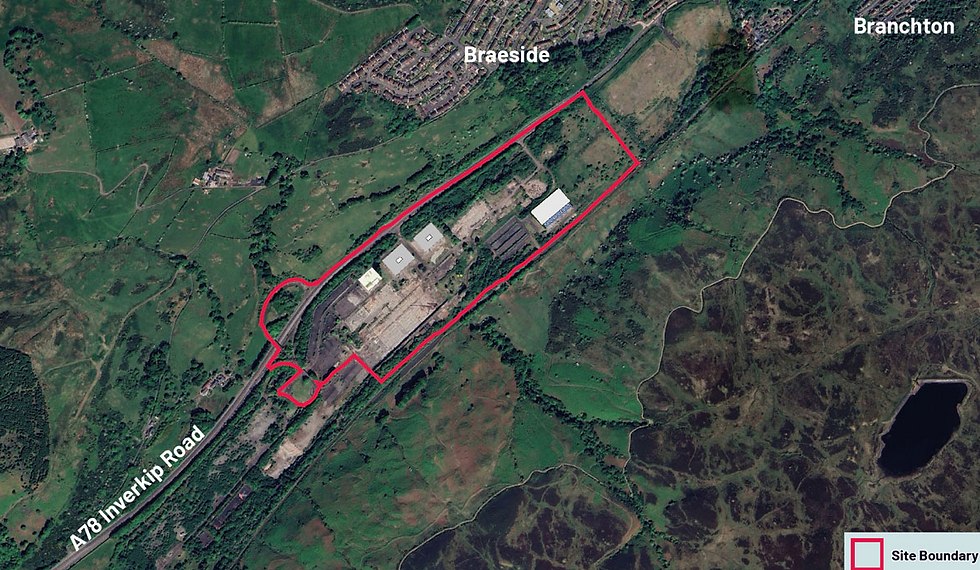
Then there is Spango Valley. IBM operated at the Greenock site from 1954 until 2017. Now Slate Island Developments is proposing four data centre buildings providing around 80,000 sq m of digital infrastructure on part of the former technology campus.
There is an obvious symmetry in bringing technology investment back to a place associated with the industry for more than six decades. But the project also illustrates where significant development capital is looking for opportunity. Data centres require large sites, connectivity and, crucially, access to substantial quantities of reliable power. The separately proposed battery energy storage system alongside Spango Valley reinforces how closely property and energy infrastructure are becoming intertwined.
Taken together, these stories suggest that the next phase of development may be defined less by how much gets built than by how convincingly investment can be justified.
Capital is available, as Cushman & Wakefield's latest life sciences figures demonstrate - global venture capital investment reached $29.9bn during the first half of 2026, up 30% year-on-year.
But investors and occupiers have recent experience of what happens when enthusiasm runs ahead of demand. That makes existing infrastructure, established locations, adaptable buildings and clear occupant requirements increasingly valuable.
Whether it is Network Rail choosing to overhaul Princes Exchange, Sky consolidating in Livingston, Plymouth finding new uses for its Civic Centre or developers attempting to reinvent IBM's former Greenock campus for the AI era, the common denominator is purpose.
One to Watch: The corporate office consolidation cycle
Sky's Livingston campus and Network Rail's investment in Princes Exchange deserve to be watched beyond the individual projects. For several years, debate around offices has focused on how much space businesses will need following the rise of hybrid working. We may now be moving into the next phase where companies are acting on the answer.
That does not necessarily mean widespread retreat from offices. It can mean consolidating multiple locations into one stronger campus, as Sky is doing, or investing substantially in a strategically located existing building, as Network Rail is doing in Leeds.
If more large employers follow that pattern, the consequences for office markets could be significant. The best-connected, highest-quality buildings should attract investment, while secondary assets without a compelling reason for occupation face a much harder question about their future.
Risk Radar: Supply can still outrun demand
Life sciences provides the clearest warning this week. Investment conditions are improving dramatically, yet global laboratory vacancy still stands at 24.2% and substantial recently developed space is continuing to reach the UK market. There is an important distinction between confidence in an industry and demand for its real estate.
The same principle applies elsewhere. Growth in AI does not automatically make every proposed data centre viable, just as renewed enthusiasm for offices does not rescue every ageing workplace. For developers, the risk is assuming that strong structural demand for a sector guarantees demand for individual buildings.
After several years of economic uncertainty, occupiers and capital appear increasingly willing to invest again, but they are also becoming more particular about where that money goes.